
Construction factoring is a specialized type of invoice factoring adapted to work in the construction industry. It helps subcontractors improve their cash flow by financing their net-30 to net-60 invoices from commercial clients and general contractors (GCs).
This article explains how construction factoring helps you, how it works, its advantages, and its limitations. The article will help you determine if it’s the right solution for your company. We cover the following:
- Do you offer net-30 terms?
- How does construction factoring work?
- Advance rates
- How much does it cost?
- Why can’t retainage invoices be financed?
- How is it different from invoice factoring?
- Advantages
- Limitations
- Typical business uses
- Do you qualify for construction factoring?
1. Do you offer net-30 terms?
Construction subcontractors typically have to offer net-30 (or longer) terms to their business clients. Their clients require this as a condition for doing business with them. However, offering payment terms is often a challenge for subcontractors, putting them in a difficult position.
Subcontractors need funds to pay their employees and cover materials, equipment rentals, and other expenses. They can’t wait for weeks to get paid. This situation can lead to cash flow problems, especially if your company does not have a cash reserve.
a) Two possible solutions
There are two ways to handle this problem. The simplest option is to offer your clients a discount for paying quickly. Offering clients a 2% discount if they pay within ten days is typical. However, this can be negotiated.
This strategy has one limitation. Your clients retain the option to pay on their usual terms. Consequently, you can’t always rely on early payments.
The most reliable solution is to use financing. It allows you to handle the financial gap between invoicing and payment effectively. One of the most effective solutions for this challenging problem is construction factoring. It is designed specifically for subcontractors who want to improve their cash flow.
2. How does construction factoring work?
Construction factoring is a specialized type of invoice factoring that has been adapted to work with the construction industry. Subcontractors can use the program to get financing for invoices tied to completed commercial work or work segments.
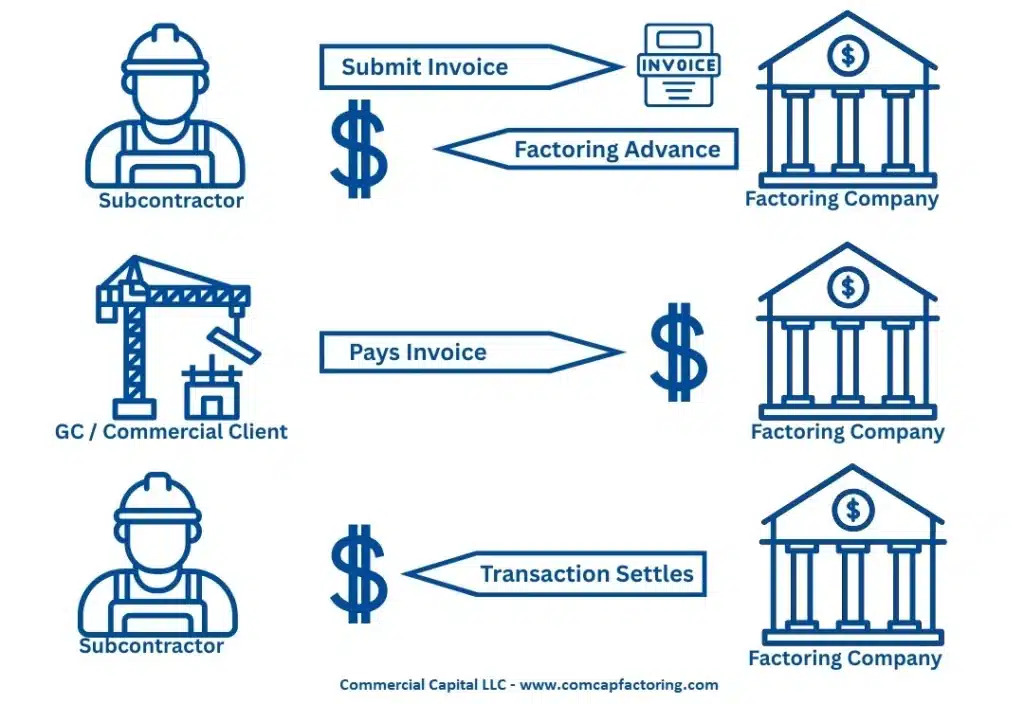
Invoices are financed in two installments. The first installment provides most of the funds, with a portion held in reserve. The second installment settles the transaction. The following diagram shows the key steps of the construction factoring process.
a) First installment
The first installment is called the advance. On average, it covers 75% – 85% of the invoice. The advance varies based on the invoice details and is deposited once the factor processes the invoice.
b) Second installment
The second installment covers the remaining 15% – 25%, less the factoring fee. It is deposited once your customer pays the invoice in full. This installment settles the transaction for the invoice.
3. Advance rates
The average advance rate for construction factoring is between 75% and 85% of the invoice, net of retainage. However, factoring companies typically adjust the advance to reflect the risk profile of the transaction and invoice. When determining the advance rate, factoring companies consider the creditworthiness of the general contractor or commercial customer, payment terms, payment history, and the potential for disputes or offsets.
4. How much does it cost?
Construction factoring companies base their rates on the size of the line, the quality of your invoices, and the creditworthiness of your customers. Usually, companies with high factoring volumes and high-quality accounts receivable qualify for lower rates.
Rates typically range from 1.5% to 2.75% per 30 days and follow a tiered structure. Examples include:
Construction factoring rates are usually higher than conventional factoring rates, although the difference is usually small. This is due to the additional risk associated with progress payments and construction projects.
5. Why can’t retainage invoices be financed?
Construction invoices are typically subject to retainage of 5% to 10%, depending on the contract. Retainage is a percentage of the invoice that is withheld until certain requirements or milestones are met. Retainage is typically used to address potential disputes and other issues that may arise.
Factoring companies usually don’t finance the retainage component of an invoice. Even if you could finance retainage, we don’t think it’s a good idea. In our experience, these invoices are more likely to be affected by two problems:
a) Disputes
Retainage payments are more susceptible to disputes because they are intended to protect against incomplete or defective work and other contractual issues. Consequently, factoring them can require the client to repay the advance and associated fees if a dispute delays payment or makes the invoice uncollectible.
b) Payment timing
Retainage payments are usually made once major milestones have been met or the project has been completed. These payments can take months or longer, especially on large projects. This is a problem because most factoring agreements specify that an invoice cannot remain unpaid for more than 90 days.
6. How is it different from invoice factoring?
Construction factoring is a specialized form of invoice factoring. However, it differs from invoice factoring in five key areas.
a) Progress billing
Conventional factoring companies typically don’t work with clients that use progress billing. This is because progress billing invoices are difficult to process and carry a higher risk.
Construction factoring companies have adapted their workflow to handle progress invoices. This allows them to work with subcontractors.
b) Pay-when-paid clauses
Construction contracts often include a “pay-when-paid” clause. These provisions allow general contractors to delay paying subcontractors until they receive payment from the project owner.
Construction factoring companies can finance invoices with pay-when-paid clauses. Unlike traditional factoring companies, they are familiar with these payment arrangements and can accommodate them.
c) Invoice verification
Factoring companies typically verify invoices before funding them. This process is usually straightforward for conventional invoices. However, construction invoices can be more complex due to the nature of construction contracts and billing practices.
Construction factoring programs are designed to handle these complexities, including progress payments, retainage, and other construction-specific billing arrangements.
d) Minimums
Operating a construction factoring program is labor-intensive for the finance company. Consequently, construction factoring companies can work only with subcontractors that invoice above a specified minimum. Minimums vary by company but are about $50,000 per month.
e) Pricing
Construction factoring rates are typically higher than those of conventional factoring lines of the same size. This is done to account for the risk profile and process management. Learn more about factoring rates.
f) Advances
Construction factoring programs typically advance 75% to 85% of the invoice, which is somewhat lower than conventional factoring advances. The lower advance helps manage the additional risks associated with construction invoices, including potential underpayments, disputes, and billing adjustments. The specific advance rate depends on the risk profile of the transaction.
7. Advantages
Factoring plans have several advantages over other solutions. The most important ones include the following.
a) Improves cash flow
Construction factoring is designed to reduce cash flow problems caused by slow-paying customers. It can improve cash flow quickly, usually shortly after deployment.
b) Simpler qualification
The program has simple qualification criteria. It is easier to obtain than conventional bank financing and has fewer covenants.
c) Quick deployment
Factoring lines can be deployed quickly. Most lines can be deployed in a week or two as long as the finance company gets all the information they need promptly.
d) Simple line increases
The factoring line is tied to your sales to high-quality commercial customers and general contractors. The line can be increased quickly, provided your customers have good business credit, and your company can deliver the products and services.
8. Limitations
Construction factoring is not for everyone. The program has some limitations that construction companies must keep in mind.
a) Available only to subcontractors or suppliers
The program is available only to subcontractors or construction materials suppliers. Unfortunately, construction factoring companies cannot finance General Contractors.
b) Cannot finance residential clients
Factoring can be used only to finance invoices due from commercial clients or GCs. It cannot be used to finance invoices from residential clients.
c) Your clients must have good business credit
The program uses your invoices as collateral. Consequently, it can only finance invoices payable by commercial clients and GCs with good business credit.
d) It can be expensive
Construction factoring is comparatively expensive. It should be used only by companies with higher profit margins.
9. Typical business uses
The following examples show how construction factoring is used in real-world situations. Each one addresses a common cash flow challenge faced by businesses.
a. Small commercial painting company
A small commercial painting subcontractor has won a contract to paint the buildings of an office park. This large contract is a great opportunity for the company. The subcontractor can invoice for the project in stages. However, invoices are paid in 45 days, and the subcontractor lacks the working capital to cover expenses while waiting for payment.
The subcontractor chooses to work with a construction factoring company because it offers a revolving solution and has simpler requirements than other alternatives. The factoring company allows the subcontractor to finance its progress invoices, providing the funds needed to operate the business.
b. Growing commercial HVAC subcontractor
A commercial HVAC subcontractor is going through a period of fast-paced growth. While profits are growing, general contractors and clients are paying invoices in 60 days. This creates a cash flow problem since the subcontractor does not have a sizable cash reserve. Consequently, the subcontractor is at risk of missing payroll.
The subcontractor evaluates its financing needs and chooses a construction factoring company with several clients in the HVAC industry. The subcontractor is able to finance invoices and cover payroll. Ultimately, the facility provides the financial flexibility the subcontractor needs to pursue its growth strategy.
c. Midsize drywall subcontractor
A midsize drywall subcontractor experiencing stable growth faces slower payments from its GC and builder clients due to a slowing economy. Instead of paying invoices in 30 days, most of its customers have started paying in 45 to 60 days. This situation creates a cash flow problem for the subcontractor.
The subcontractor does not want to finance invoices from all its customers. Instead, it only needs to finance invoices from some customers. This enables it to cover the cash flow shortfall while also providing a safety margin.
The drywall subcontractor chooses a construction factoring company that offers a selective factoring facility with an 85% advance rate. That gives the subcontractor the flexibility to finance invoices from selected customers without having to factor its entire customer base.
10. Do you qualify for construction factoring?
The qualification requirements for construction factoring are simpler than the requirements for other products. Your company must meet the following seven criteria.
a) Must be a subcontractor or supplier
The program is only available to construction subcontractors or construction materials suppliers. Unfortunately, construction factoring is not available to general contractors. This is due to the complexity of supplier payments and lien management.
b) Must work with commercial clients or GCs
You can only finance invoices from commercial clients or general contractors. Your clients must have good business credit because their invoices are the primary collateral for the transaction.
c) Can’t have a bond on the job
Note that there is no problem if the GC has a bond for the job. However, your company must not have a performance bond on the job. This is because the bonding company files a lien that prevents the factor from obtaining a first-position lien on your invoices.
d) Must not have open loans or cash advances
Your company cannot have any open loans or cash advances. This is because they typically encumber all your assets with a lien. Factoring companies need to have a first-position lien against the invoices they finance.
e) Must meet the financing minimum
Most construction factoring companies have a minimum monthly volume. The minimum varies by company, but it’s typically set at $50,000/month. Your company must invoice at least the monthly minimum to qualify.
f) No serious tax or legal issues
Your company must not have any serious tax or legal issues. If it has any issues, you should have a workout or resolution plan in place.
g) Must be incorporated or an LLC
Your company must be legally structured as a corporation or limited liability company (LLC). Sole proprietorships do not qualify.
Get more information
Are you looking for a factoring quote? We provide construction factoring at affordable terms. For more information, get an online quote or call us toll-free at (877) 300 3258.

Marco Terry is the Managing Director of Commercial Capital LLC and has over two decades of experience in asset-based finance. He has worked with small and mid-sized companies across the United States, Canada, and Australia. Marco holds a Master of Science in Finance.